

TWIA — Texas
TWIA Says Its Board Backed a Must-Accept Takeout Rule. The Roll Call Says It Failed.
The minutes name every vote on the takeout rule, and it lost. The release still says it passed, weeks before the Biennial Report goes to the Legislature.
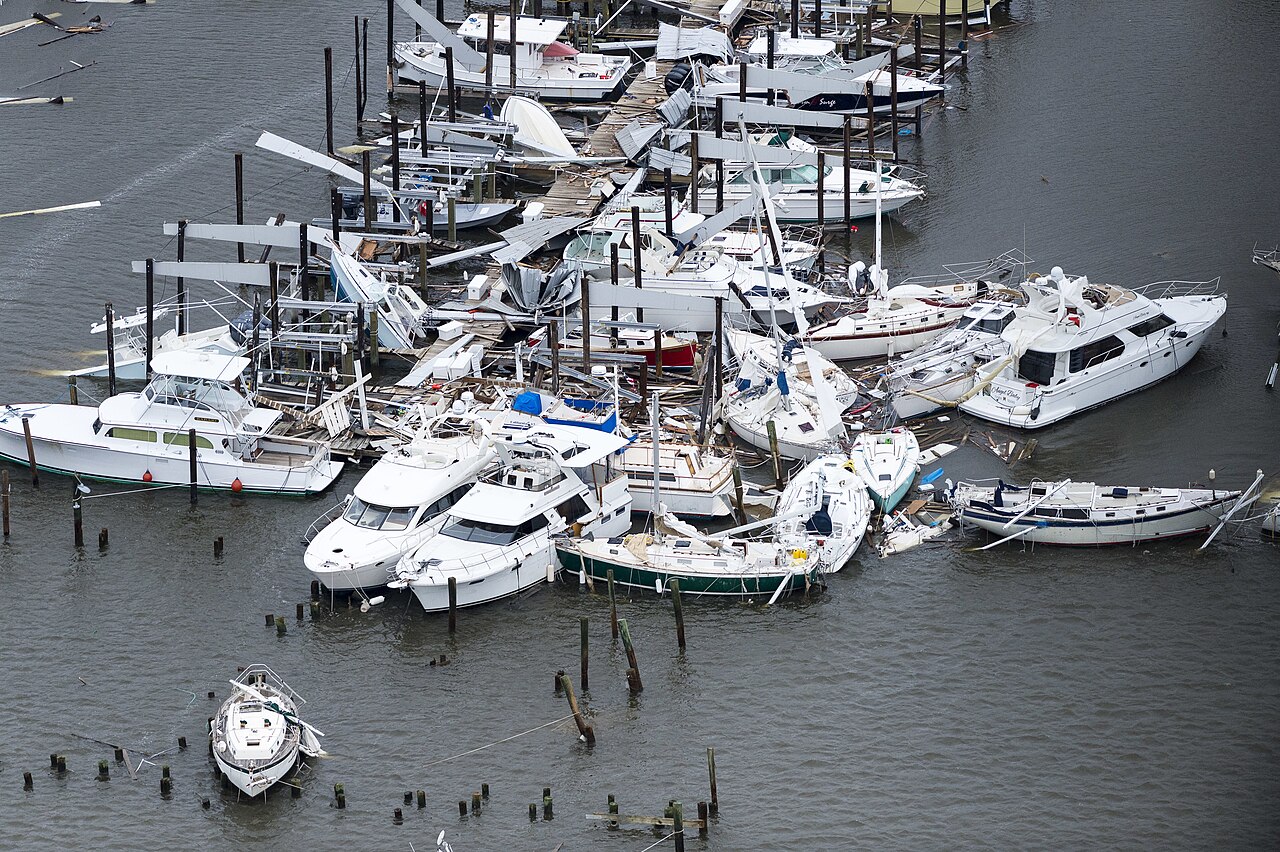
Photo: FEMA / Greg Henshall
In short
TWIA's Oct. 8, 2026 press release says its board voted to adopt a recommendation for legislation including a rule that would require policyholders to accept takeout offers. The minutes TWIA put in its Nov. 10 board packet show that motion failed 3 to 4 with one abstention, while a TWIA-paid per-risk bonus to takeout carriers passed. As of Nov. 18, 2026, no correction had been posted, and the Biennial Report is due by Dec. 31.
Three yes, four no, one abstention. TWIA's board cast those votes on Oct. 8, 2026, on a motion asking the Legislature for a rule that could make coastal policyholders accept a takeout offer. Rolando Rubiano, Jamie Carsey and John Todd voted yes. Terrilyn Tarlton Shannon, Greg Smith, Mark Shewmaker and Tim Garrett voted no, and Etti Baranoff abstained. "The motion did not pass."1
TWIA's press release says "The Board voted to adopt the following legislative recommendations," and its depopulation bullet ends with legislation "to include a premium compatibility rule, which would require the insured to accept the takeout offer."2 The bullet describes the failed motion, with "could require" hardened to "would require."1 An Oct. 9 reprint by the Independent Insurance Agents of Texas carries it too; neither copy showed a correction on Nov. 18, 2026.23
The losing motion was softer than staff's "20% Rule."5 Carsey's motion left the percentage "to be considered with market conditions," and association counsel Mike Perkins restated it as legislation "in a manner that might include a premium threshold that, if met, could require the insured to accept a takeout offer."1 Rubiano, who had asked "how does this not equate to a 20% rate increase," seconded it. He "liked the vagueness of the original motion" and would not back adding direct policyholder contact that bypassed the agent.1
The Biennial Report is due by Dec. 31, 2026 under § 2210.0025.4 The board told staff to prepare it "in accordance with what has been discussed today."1 TWIA wrote both accounts of that discussion. They cannot both be right, and only the minutes record each director's vote. Anyone pushing a must-accept rule next session can hand a legislator TWIA's own release saying the board endorsed one.
What did the board send to the Legislature?
| Item | What the Oct. 8 release says | What the minutes record |
|---|---|---|
| Takeout acceptance rule | Adopted: consider legislation including a premium compatibility rule that would require the insured to accept | Open-ended threshold motion failed, 3 yes, 4 no, 1 abstain |
| Bonus to takeout carriers | Adopted, with a multi-year renewal requirement | Passed, multi-year removal requirements; Rubiano and Tarlton Shannon opposed |
| MDL judge, § 2210.575(e) | Eliminate or make optional | Passed unanimously |
| FORTIFIED funding | Consider feasibility and possible public funding | Passed 6–2 (Rubiano, Carsey no), CRTF funding bullet removed |
| HB 3689 funding fixes | More administrative time; an alternative funding method for small shortfalls | Passed unanimously |
| Tort reform | Not listed | Will not appear in the Biennial Report |
| Agent protections, surplus lines | Not listed | Will not appear in the Biennial Report |
Our September post on the committee stage covered MDL and tort reform; the board kept only MDL.1
The bonus passed, and the record behind it is worse for homeowners. The motion authorizes "TWIA to pay a bonus per risk removed to participating carriers, subject to multi-year removal requirements and TDI’s approval," with no amount; staff's examples ran from $100 per barrier island risk to $25 at 10 miles or more inland.15 General Manager David Durden said "it would be TWIA paying the bonuses," and that "staff has not had conversations with the insurance market about what would entice them to come back."1 The State Auditor's Oct. 15, 2026 efficiency audit found no carrier application for assumption rounds 7 through 10.6 In 2022 two takeout carriers, Weston and Maison, went into receivership, "requiring the Association to rewrite more than 12,000 policies previously taken out of TWIA."1 Rubiano and Tarlton Shannon, two of the board's three First Tier Coastal Representatives, voted against the bonus; Smith, the third, made the motion.1 Rubiano said he was committed to depopulating TWIA "but not at the coastal resident’s expense."1
A takeout offer on a coastal file today
Under current law the client can say no; TWIA's policyholder page says participating companies must "Allow policyholders to decline offers, and remain with TWIA."7 Section 2210.705(1) guarantees a chance to opt out "not more than 60 days after the policyholder receives notice." Section 2210.703 caps the premium for generally comparable coverage at 115 percent of TWIA's and requires three years of renewal offers, subject to the carrier's filed rates and underwriting guidelines, and § 2210.704(b) routes the offer through the agent of record.4 Silence counts: staff's comparison table says a policyholder who takes no action within the 60 days is moved to the new carrier.45
Staff's 20% Rule would have made saying no expensive. "If the policyholder declines, they are ineligible for TWIA coverage for 3 years," and "Non-response leads to policy assumption."5 Staff wrote that it "partially mirrors" Florida, where § 627.351(6)(c)5.a. drops a primary residence from Citizens at renewal if an authorized insurer offers comparable coverage at no more than 20 percent above Citizens' renewal premium.58

When a client gets an assumption notice, log the date it arrived and tell the client in writing that the offer is optional. Check the takeout carrier's finances and receivership history, because the policy goes with it: under § 2210.702(b), TWIA "is not liable under the policy" after the assumption, and absent other terms in the TWIA–carrier agreement, the new carrier adjusts and pays claims. Subchapter L-1, TWIA's claims-dispute subchapter, does not apply to a renewed takeout policy under § 2210.703(c).4 Deadlines then come from the carrier's policy and general Texas law, the kind of limitations clock in our Fifth Circuit post. If the Biennial Report lists a comparability rule anyway, put the roll call in front of a legislator.1
We could not confirm the board approved these minutes on Nov. 10; TWIA's recap of that meeting does not mention them.9 The minutes record no tally for the bonus.1 No draft Biennial Report was on twia.org as of Nov. 18.
Takeouts, asked and answered
Can a TWIA policyholder turn down a takeout offer today?
Yes. Under Tex. Ins. Code § 2210.705(1), an assumption reinsurance agreement must give the policyholder the opportunity to opt out not more than 60 days after receiving notice, and TWIA's policyholder page says participating companies must allow policyholders to decline offers and remain with TWIA. A policyholder who does nothing within that window is moved to the new carrier.
Did TWIA's board recommend making policyholders accept takeout offers?
No. The Oct. 8, 2026 minutes record the motion failing 3 to 4 with one abstention, even in a version that left the premium threshold open. TWIA's Oct. 8 press release says the board voted to adopt a recommendation to consider legislation including a premium compatibility rule that would require the insured to accept the takeout offer, and we found no correction as of Nov. 18, 2026.
Will TWIA pay carriers to take its policies?
It depends. The board voted to recommend that the Legislature authorize TWIA to pay a bonus per risk removed, subject to multi-year removal requirements and TDI approval. No amount was set, and nothing changes unless the Legislature enacts it.
Do TWIA's claim-dispute rules follow a policy to the takeout carrier?
No, not on renewal. Tex. Ins. Code § 2210.703(c) says Subchapter L-1, TWIA's claims settlement and dispute resolution subchapter, does not apply to a policy renewed under that section. Under § 2210.702(b), TWIA is not liable under the policy once the assumption takes effect, and, except as the TWIA–carrier agreement provides, the assuming carrier adjusts and pays claims under the policy.
Sources cited
- TWIA Board of Directors Meeting Materials, Nov. 10, 2026 (Oct. 8, 2026 minutes, PDF pp. 18–24)— Texas Windstorm Insurance Association
- TWIA Board Reviews Budget, Advances Legislative Recommendations (Oct. 8, 2026)— Texas Windstorm Insurance Association
- TWIA Board Reviews Budget, Advances Legislative Recommendations (reprint, Oct. 9, 2026)— Independent Insurance Agents of Texas
- Tex. Ins. Code ch. 2210 (§§ 2210.0025, 2210.575, 2210.701–2210.705)— Texas Legislature
- Legislative & External Affairs materials for the Oct. 8, 2026 Board meeting (depopulation proposals, pp. 8–10)— Texas Windstorm Insurance Association
- TWIA Board of Directors Meeting Materials, Nov. 10, 2026 (State Auditor's Office efficiency audit, Report No. 27-009, PDF pp. 81–92)— Texas Windstorm Insurance Association
- Depopulation: Information for Policyholders— Texas Windstorm Insurance Association
- Fla. Stat. § 627.351(6)(c)5.a.— Florida Legislature
- TWIA Board Votes on 2027 Operating Budget at Corpus Christi Meeting (Nov. 10, 2026 recap)— Texas Windstorm Insurance Association
Built for where claims are going.
Carrier automation is not slowing down. claimOS gives the recovery side the same leverage: AI drafting grounded in the file, weather evidence on demand, and a record that holds up under review.