
State legal — Iowa
A $525,000 Limit, a $210,000 Check, and Iowa's Agreed Value Trap
A dec-page Agreed Value date did not turn a $525,000 limit into the payout on a total fire loss. The valuation clause and the ACV notice set the number.
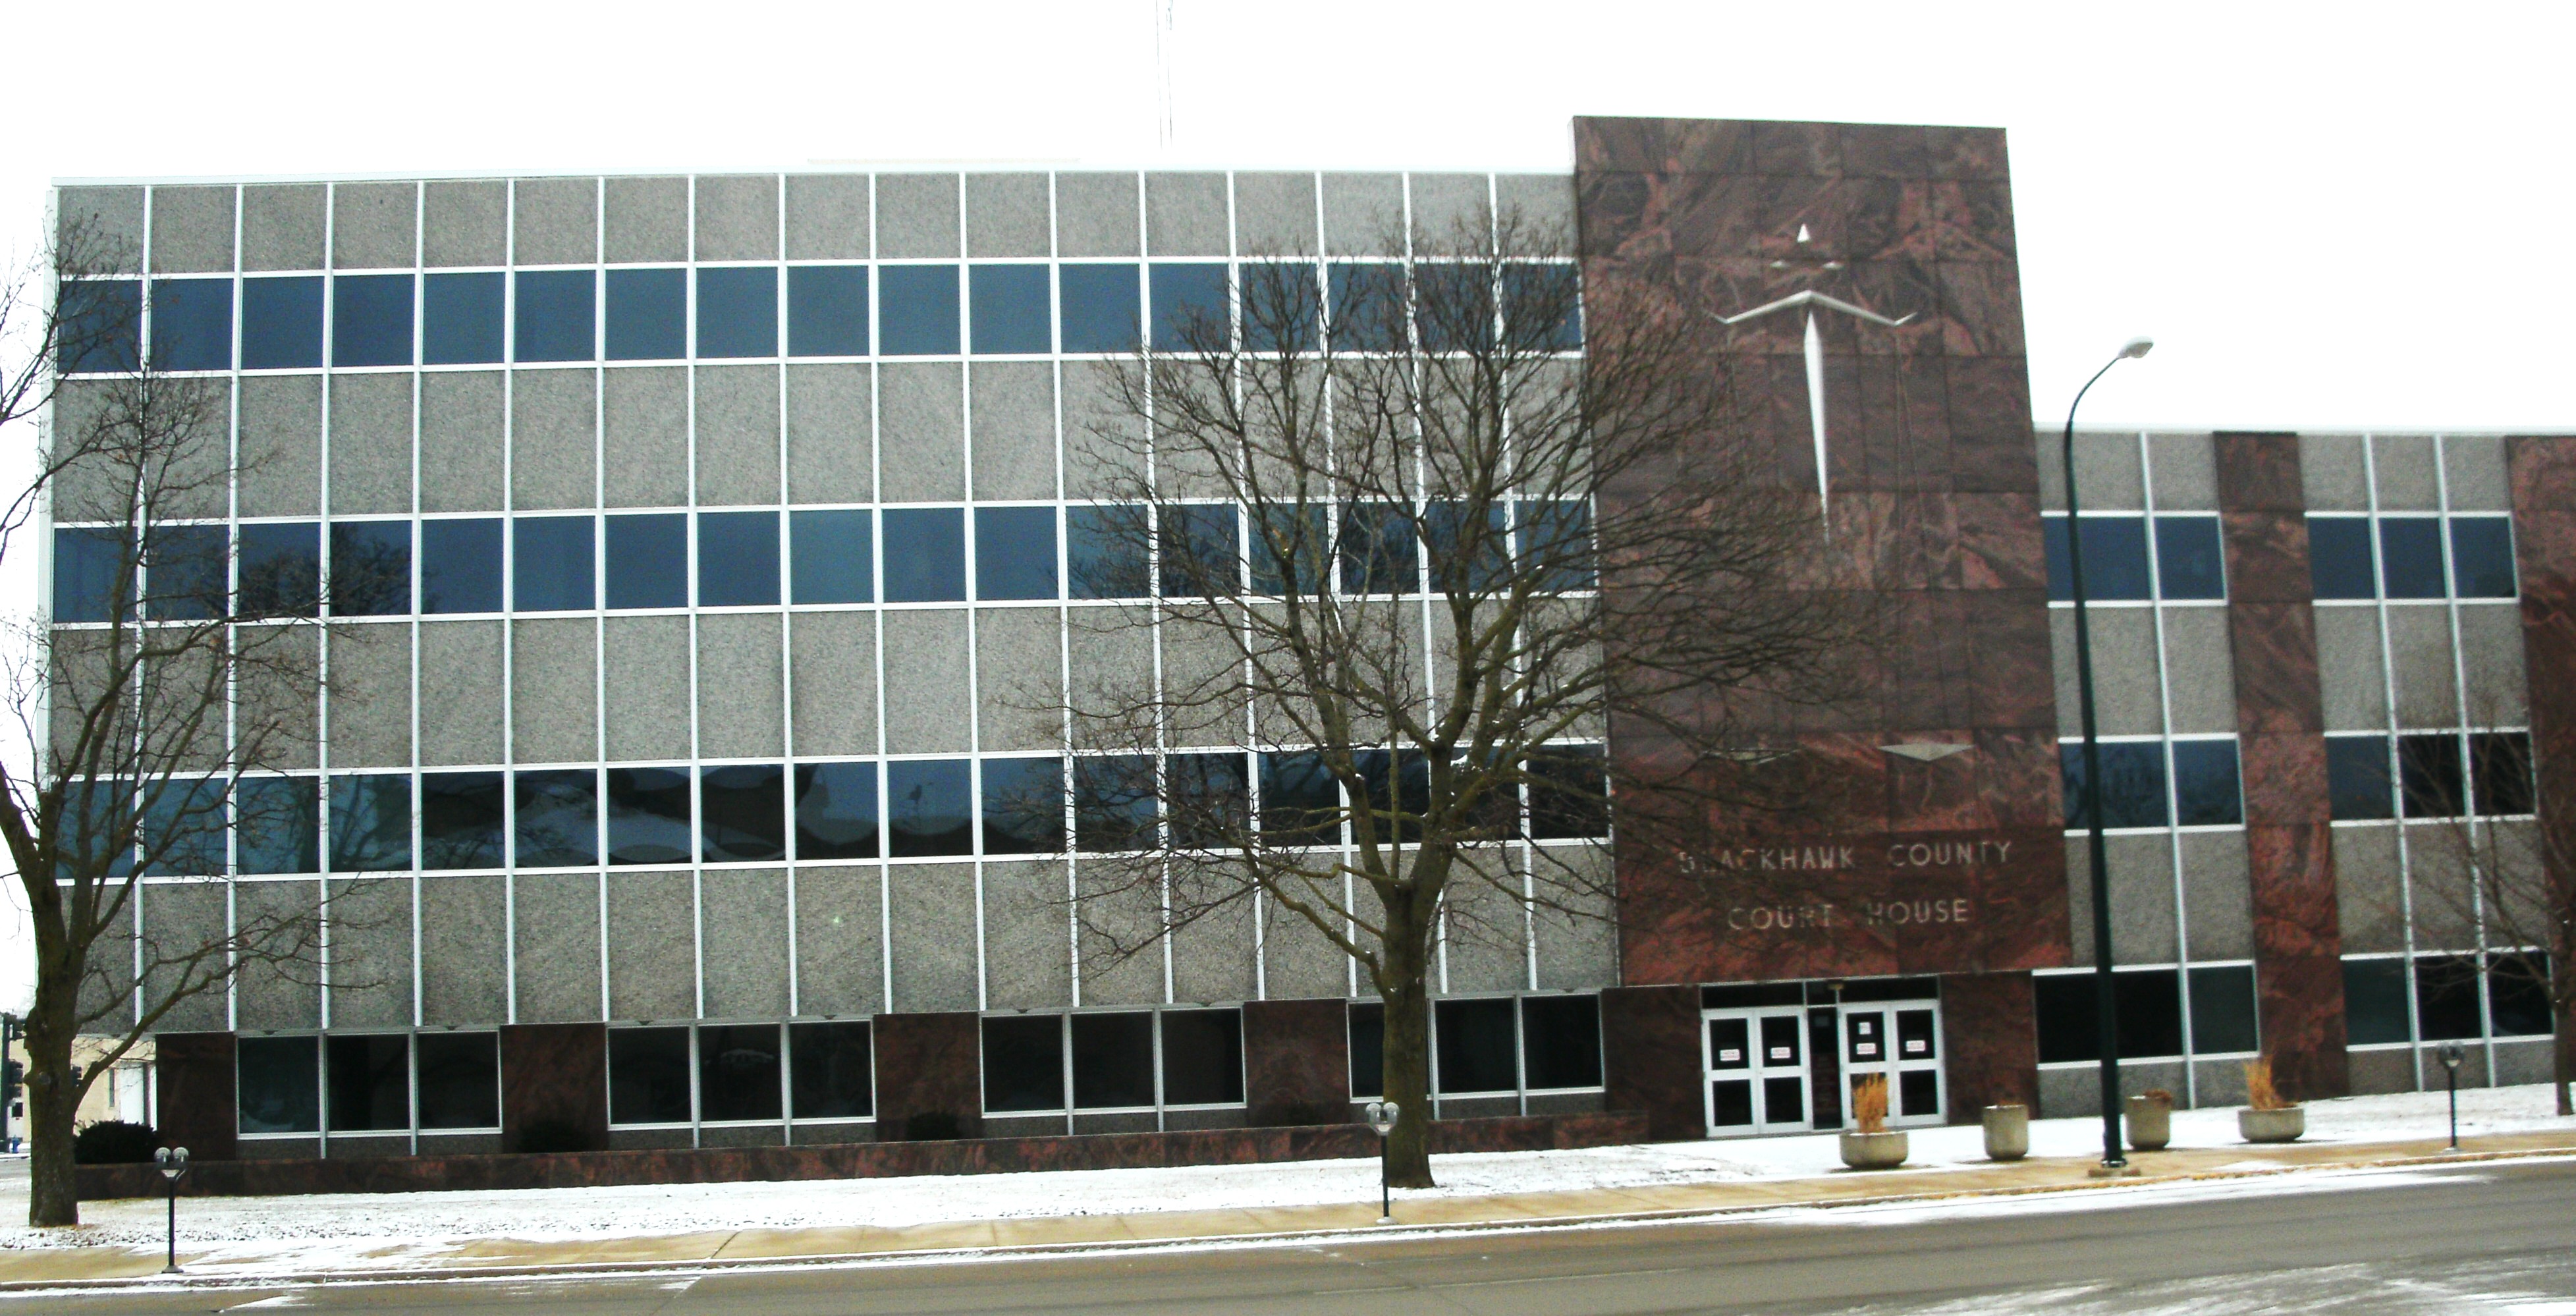
Photo: RifeIdeas / CC BY-SA 3.0 via Wikimedia Commons
In short
In The Rasmusson Company v. United Fire & Casualty Co., No. 25-1647, the Iowa Court of Appeals (Sept. 23, 2026) affirmed a directed verdict for the carrier. A Cedar Falls commercial building was a total fire loss under a $525,000 limit, and the carrier paid a $210,000 market-value ACV. The court held the limit was a ceiling and that the dec-page Agreed Value language only removed coinsurance.
A fire destroyed Rasmusson's commercial building in Cedar Falls, and the declarations page showed a $525,000 limit1 beside the words "Agreed Value Expiration Date: 08/01/2022."1
The owner read that as a promise to pay the limit and came to the table with a rebuild quote of $584,615.1 United Fire's appraiser worked from sales of similar properties, reached $210,000, and the carrier paid that amount.1
On September 23, 2026, the Iowa Court of Appeals affirmed a directed verdict for the insurer in The Rasmusson Company v. United Fire & Casualty Co., No. 25-1647.1 The policy covered the building at "actual cash value as of the time of loss or damage," and the panel quoted the Iowa Supreme Court: "The word 'limit' denotes a maximum possible amount, not a guaranteed fixed amount."1 The policy defined Agreed Value as an optional coverage that removes the coinsurance condition, and the court found no ambiguity in it. The owner's talk with the underwriter did not change the policy's terms.1
The policy also carried a notice, attributed to the Iowa Insurance Division, setting ACV at market value where a regular market exists and at repair or replacement cost less depreciation otherwise.1 The opinion cites no rule behind that notice. Division Bulletin 09-03, dated March 5, 2009, asked insurers to give notice of ACV valuation methods.2
Pull the valuation clause and any ACV notice at intake, because they set the number the dec page only summarizes. Test whether a regular market exists for the building, and pin down the valuation method in writing before an appraisal fixes the figure (see another Iowa fire claim that went through appraisal). This is an intermediate appellate decision, so check for further review before relying on it.
Sources cited
Statutory clocks, tracked on every file.
claimOS calendars these deadlines automatically on each claim: acknowledgement, decision, payment, and the suit limitation, each with its code section attached and visible to the whole team.